Whether you file your income tax return early or at the last minute, there are ways to simplify the process and reduce what you owe – or even increase your refund – before the deadline.
Filing Simplification Tip
Once you receive your W-2 and/or 1099 tax forms, see what income tax bracket you fall under to determine whether you should itemize expenses or take the standard deduction. Thinking about this step first can save you a lot of time. If you don’t come near the standard deduction amount, you will not be itemizing expenses. And if you are not itemizing expenses, you won’t have to gather all the receipts (e.g., mortgage interest, property tax, state and local income taxes, and sales tax paid in 2024).
2024 Tax Season Income Tax Brackets
Single filer
Married filing separately
Married filing jointly (includes qualifying widow/er)
Head of Household
Tax Rate
$0 to $11,600
$0 to $11,600
$0 to $23,200
$0 to $16,550
10%
$11,601 to $47,150
$11,601 to $47,150
$23,201 to $94,300
$16,551 to $63,100
12%
$47,151 to $100,525
$47,151 to $100,525
$94,301 to $201,050
$63,101 to $100,500
22%
$100,526 to $191,950
$100,526 to $191,950
$201,051 to $383,900
$100,501 to $191,950
24%
$191,951 to $243,725
$191,951 to $243,725
$383,901 to $487,450
$191,951 to $243,700
32%
$243,726 to $609,350
$243,726 to $365,600
$487,451 to $731,200
$243,701 to $609,350
35%
$609,351 or more
$365,601 or more
$731,201 or more
$609,351 or more
37%
2024 Tax Season Standard Deductions
Single filer and married filing separately
Married filing jointly (includes qualifying widow/er)
Head of Household
$14,600
$29,200
$21,900
Retirement Saving Tips
It’s not too late to contribute to an IRA. Both the traditional and Roth IRAs allow you to make contributions for 2024 up until the tax-filing deadline of the following year – which this year is Tuesday, April 15. The advantage to this later deadline is that you can complete your taxes before they are due, then adjust them to reduce your tax liability if needed by contributing to your IRA. The total maximum contribution you can make to all of your IRAs combined (both Roths and traditional) is $7,000 for 2024 or $8,000 if you are 50 years or older.
However, if you have a Roth IRA, there are restrictions to contributions based on your 2024 income. You may make the maximum contribution to your Roth only if your 2024 modified adjusted gross income (MAGI) is less than a certain threshold.
Filing Status
MAGI
Contribution amount
Single and Head of Household filers
Below $146,000
Between $146,001 and 161,000
Above $161,000
$7,000/$8,000 (age 50+)
Phased (IRS Worksheet 2-2)
Nothing
Married filing jointly
(includes qualifying widow/er)
Below $230,000
Between $230,000 and $240,000
Above $240,000
$7,000/$8,000 (age 50+)
Phased (IRS Worksheet 2-2)
Nothing
Be aware that the amount of deduction you can claim for a traditional IRA contribution may be limited if you or your spouse are covered by a retirement plan at work.
Filing Status
MAGI
Deduction amount
Single and Head of Household filers
$77,000 or less
Between $77,000 and 87,000
$87,000 or more
Full deduction
Partial (IRS Worksheet 1-2)
None
Married filing jointly
(includes qualifying widow/er)
$123,000 or less
Between $123,000 and 143,000
$143,000 or more
Full deduction
Partial (IRS Worksheet 1-2)
None
Married filing separately
Less than $10,000
$10,000 or more
Partial (IRS Worksheet 1-2)
None
If you make a traditional and/or Roth IRA contribution by the April 15 deadline, you may qualify for the Retirement Saver’s Credit (also available if you contributed to an employer plan by Dec. 31, 2024). The maximum credit is $1,000 ($2,000 for married couples), and it can increase your refund or reduce the tax you owe. However, the saver’s credit is subject to other deductions, credits, and income restrictions.
Filing Status
MAGI
Single and Married filing separately
up to $57,375
Married couples filing jointly
(includes qualifying widow/er)
up to $76,500
Head of Household Filers
up to $57,375
Work with an experienced tax preparer to take advantage of legitimate deductions and credits to ensure that you only pay what is required for your situation.
Tips for Tax Season
January 1, 2025 · Blog, Financial Planning, Uncategorized
⏱ 4 min read
Whether you file your income tax return early or at the last minute, there are ways to simplify the process and reduce what you owe – or even increase your refund – before the deadline.
Filing Simplification Tip
Once you receive your W-2 and/or 1099 tax forms, see what income tax bracket you fall under to determine whether you should itemize expenses or take the standard deduction. Thinking about this step first can save you a lot of time. If you don’t come near the standard deduction amount, you will not be itemizing expenses. And if you are not itemizing expenses, you won’t have to gather all the receipts (e.g., mortgage interest, property tax, state and local income taxes, and sales tax paid in 2024).
2024 Tax Season Income Tax Brackets
Single filer
Married filing separately
Married filing jointly (includes qualifying widow/er)
Head of Household
Tax Rate
$0 to $11,600
$0 to $11,600
$0 to $23,200
$0 to $16,550
10%
$11,601 to $47,150
$11,601 to $47,150
$23,201 to $94,300
$16,551 to $63,100
12%
$47,151 to $100,525
$47,151 to $100,525
$94,301 to $201,050
$63,101 to $100,500
22%
$100,526 to $191,950
$100,526 to $191,950
$201,051 to $383,900
$100,501 to $191,950
24%
$191,951 to $243,725
$191,951 to $243,725
$383,901 to $487,450
$191,951 to $243,700
32%
$243,726 to $609,350
$243,726 to $365,600
$487,451 to $731,200
$243,701 to $609,350
35%
$609,351 or more
$365,601 or more
$731,201 or more
$609,351 or more
37%
2024 Tax Season Standard Deductions
Single filer and married filing separately
Married filing jointly (includes qualifying widow/er)
Head of Household
$14,600
$29,200
$21,900
Retirement Saving Tips
It’s not too late to contribute to an IRA. Both the traditional and Roth IRAs allow you to make contributions for 2024 up until the tax-filing deadline of the following year – which this year is Tuesday, April 15. The advantage to this later deadline is that you can complete your taxes before they are due, then adjust them to reduce your tax liability if needed by contributing to your IRA. The total maximum contribution you can make to all of your IRAs combined (both Roths and traditional) is $7,000 for 2024 or $8,000 if you are 50 years or older.
However, if you have a Roth IRA, there are restrictions to contributions based on your 2024 income. You may make the maximum contribution to your Roth only if your 2024 modified adjusted gross income (MAGI) is less than a certain threshold.
Filing Status
MAGI
Contribution amount
Single and Head of Household filers
Below $146,000
Between $146,001 and 161,000
Above $161,000
$7,000/$8,000 (age 50+)
Phased (IRS Worksheet 2-2)
Nothing
Married filing jointly
(includes qualifying widow/er)
Below $230,000
Between $230,000 and $240,000
Above $240,000
$7,000/$8,000 (age 50+)
Phased (IRS Worksheet 2-2)
Nothing
Be aware that the amount of deduction you can claim for a traditional IRA contribution may be limited if you or your spouse are covered by a retirement plan at work.
Filing Status
MAGI
Deduction amount
Single and Head of Household filers
$77,000 or less
Between $77,000 and 87,000
$87,000 or more
Full deduction
Partial (IRS Worksheet 1-2)
None
Married filing jointly
(includes qualifying widow/er)
$123,000 or less
Between $123,000 and 143,000
$143,000 or more
Full deduction
Partial (IRS Worksheet 1-2)
None
Married filing separately
Less than $10,000
$10,000 or more
Partial (IRS Worksheet 1-2)
None
If you make a traditional and/or Roth IRA contribution by the April 15 deadline, you may qualify for the Retirement Saver’s Credit (also available if you contributed to an employer plan by Dec. 31, 2024). The maximum credit is $1,000 ($2,000 for married couples), and it can increase your refund or reduce the tax you owe. However, the saver’s credit is subject to other deductions, credits, and income restrictions.
Filing Status
MAGI
Single and Married filing separately
up to $57,375
Married couples filing jointly
(includes qualifying widow/er)
up to $76,500
Head of Household Filers
up to $57,375
Work with an experienced tax preparer to take advantage of legitimate deductions and credits to ensure that you only pay what is required for your situation.
Disclaimer
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
Here we are in yet another new year. The obligations and celebrations are over. Chances are, you’ve spent a fair amount over the holidays and might need a plan to help kickstart 2025 with some actionable financial goals. Here are a few ideas.
Create a Budget
This one never gets old. Why? It’s one of the keys to successful budgeting. You can set up a budget for the year that includes essentials, entertainment, and nice-to-haves, aka your Wish Farm. Then place it in your planner or app – there are many good ones out there. In fact, there’s a TikTok trend called loud budgeting, where people openly discuss their financial goals on social media – why they do or don’t want to buy something. If this is your thing and it helps you stay on track, go for it! If not, a good old-fashioned planner works just as well.
Bucket Your Money
This is the next step after the aforementioned. Split your money into categories: food, rent/ mortgage, utilities, medical, entertainment, vacation, etc. Apps can help you parse out these groups. You might also set up separate banking accounts for some of the necessities so you’ll know to leave them alone and not dip into them, tempting as it may be.
Set Up Auto-Drafts
Let’s say you’re saving for your child’s college fund or a down payment on a car. When you create an auto-draft for a certain amount, you’ll never miss that deposit. If you need to tweak the amount during the year, do it. Here’s the bottom line: 1) You’ll learn to live on less, and 2) you’ll be on the way to making your dreams come true.
Look for Savings Deals
Don’t just settle for the interest rate your current bank is offering. There are many options out there to grow your money. But first, do you want to lock into a fixed rate? This can be useful for long-term goals, such as buying a property. Or do you want an easy-to-access account with the ability to withdraw cash for emergencies or short-term needs like birthday or wedding gifts? Shop around.
Cancel Seldom-Used Subscriptions
Scour your bank statement. Do you need all those online magazine subscriptions? How about newsletters you pay for – the ones you rarely read? Purge your subscriptions, then see how much you’ll save. If you’re so inclined, you could put these dollars toward a gym membership. January is when all the specials appear: zero joining fees, if not a seriously cut rate.
Start a Savings Challenge
Try putting away a small amount every month. Get in the habit of emptying your pockets or coin purse. Safeguard your coins in a mason jar, and then transfer them monthly into your savings account. The next month, increase how much you contribute. Pennies, nickels, dimes, and quarters add up! After a year, you might be surprised how much you’ve saved.
Decide on Goals
These can be small or large. It’s up to you. Spend some time thinking about what’s important. Do you want to remodel your house? Contribute to a beloved charity or cause? One resource you might want to consider setting up is an emergency spending pot. This is essential and sometimes overlooked. Regardless of what you decide, figure out your parameters: how much to set aside, how often, and by when. Having financial targets gives you something to look forward to. Best of all, when you achieve your goal, it’s an awesome feeling.
More often than not, New Year’s resolutions center on getting physically fit. But if you stay the course with your finances, you’ll most definitely be, wait for it … fiscally fit!
Sources
10 things you can do right now to start 2025 with fresh finances
January 1, 2025 · Blog, Tip of the Month, Uncategorized
⏱ 4 min read
Here we are in yet another new year. The obligations and celebrations are over. Chances are, you’ve spent a fair amount over the holidays and might need a plan to help kickstart 2025 with some actionable financial goals. Here are a few ideas.
Create a Budget
This one never gets old. Why? It’s one of the keys to successful budgeting. You can set up a budget for the year that includes essentials, entertainment, and nice-to-haves, aka your Wish Farm. Then place it in your planner or app – there are many good ones out there. In fact, there’s a TikTok trend called loud budgeting, where people openly discuss their financial goals on social media – why they do or don’t want to buy something. If this is your thing and it helps you stay on track, go for it! If not, a good old-fashioned planner works just as well.
Bucket Your Money
This is the next step after the aforementioned. Split your money into categories: food, rent/ mortgage, utilities, medical, entertainment, vacation, etc. Apps can help you parse out these groups. You might also set up separate banking accounts for some of the necessities so you’ll know to leave them alone and not dip into them, tempting as it may be.
Set Up Auto-Drafts
Let’s say you’re saving for your child’s college fund or a down payment on a car. When you create an auto-draft for a certain amount, you’ll never miss that deposit. If you need to tweak the amount during the year, do it. Here’s the bottom line: 1) You’ll learn to live on less, and 2) you’ll be on the way to making your dreams come true.
Look for Savings Deals
Don’t just settle for the interest rate your current bank is offering. There are many options out there to grow your money. But first, do you want to lock into a fixed rate? This can be useful for long-term goals, such as buying a property. Or do you want an easy-to-access account with the ability to withdraw cash for emergencies or short-term needs like birthday or wedding gifts? Shop around.
Cancel Seldom-Used Subscriptions
Scour your bank statement. Do you need all those online magazine subscriptions? How about newsletters you pay for – the ones you rarely read? Purge your subscriptions, then see how much you’ll save. If you’re so inclined, you could put these dollars toward a gym membership. January is when all the specials appear: zero joining fees, if not a seriously cut rate.
Start a Savings Challenge
Try putting away a small amount every month. Get in the habit of emptying your pockets or coin purse. Safeguard your coins in a mason jar, and then transfer them monthly into your savings account. The next month, increase how much you contribute. Pennies, nickels, dimes, and quarters add up! After a year, you might be surprised how much you’ve saved.
Decide on Goals
These can be small or large. It’s up to you. Spend some time thinking about what’s important. Do you want to remodel your house? Contribute to a beloved charity or cause? One resource you might want to consider setting up is an emergency spending pot. This is essential and sometimes overlooked. Regardless of what you decide, figure out your parameters: how much to set aside, how often, and by when. Having financial targets gives you something to look forward to. Best of all, when you achieve your goal, it’s an awesome feeling.
More often than not, New Year’s resolutions center on getting physically fit. But if you stay the course with your finances, you’ll most definitely be, wait for it … fiscally fit!
Sources
10 things you can do right now to start 2025 with fresh finances
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
A Dec. 3 proposal from FASB’s Accounting Standards Update (ASU) might provide some flexibility for private businesses and select nonprofits. “Financial Instruments – Credit Losses (Topic 326)” looks at measuring credit losses for contract assets and accounts receivable for these entities.
When it comes to determining projected credit losses for current accounts receivables and current contract assets, businesses face immense resource needs and reporting requirements, including for assets acquired prior to the publication dates of financial statements.
With public comments being received through Jan. 17, 2025, industry professionals have reported that when it comes to gauging projected credit losses for current contract assets and current accounts receivable, there’s a massive undertaking and validation necessary for assets collected prior to financial statement issuance dates. Industry professionals argue that being able to factor in collections post-balance sheet date in calculating expected credit losses would reduce the complexity for preparers, whereas, for third parties, including investors and others who utilize financial statements, it would provide them with valuable data.
FASB proposed an amendment to ASC 326 207 to allow private companies and certain not-for-profit entities to employ a more flexible and efficient way to better gauge their projected credit losses for current contract assets and accounts receivable that originate from transaction accounts under ASC 606.
Working with the Private Company Council (PCC) to look at stakeholders’ concerns that estimating projected credit losses can be exorbitant and complicated for financial proceedings, FASB is soliciting comments on whether or not to expand the scope of entities included for ASU standards, along with different asset classes.
Current Criteria
According to ASC 326-20, when expected credit losses are estimated by entities, an entity must evaluate their ability to garner cash flows via the lens of contemporary economic circumstances, rational and documented projections, and past losses. Past losses may need to be fine-tuned to approximate project credit losses if past circumstances change from present conditions or from well-ground estimates and documented projections. Another consideration when formulating credit loss projections is that entities aren’t required to factor in collections obtained post-balance sheet date.
Proposed Additions
When it comes to the proposed additions, FASB speaks to a practical expedient and an accounting policy election. The practical expedient concerns an entity’s well-grounded, data-dependent projections. If an entity chooses the practical expedient, it would be able to factor in collection activity beyond the balance sheet date when projecting expected credit losses.
Practical Expedient
To formulate projections that are rational and based on verified accounting details, this so-called practical expedient can be chosen by the entity that assumes its present balance sheet conditions will last for the entire projection time frame. Choosing a practical expedient also implies that an entity’s accounting policy will factor in collection activity past its balance sheet date when gauging expected credit losses. Specifically, under 326-20-30-10C for the practical expedient, during the projection time frame, an entity will maintain the exact circumstances of the balance sheet throughout the rational and data-based projection period.
If a business, for example, has determined a particular client is facing monetary challenges, it would account for its client’s financial issues through projections of estimated expected credit losses for said client, even though it has not impacted the business’ historical loss experience or if the business is up to date as of the balance sheet date.
Accounting Policy Election
Per 326-20-30-10E, when a practical expedient from 326-20-30-10C through 30-10D is chosen by entities for their accounting policy election when projecting credit losses, it signals that the entity factors in collection activity after the balance sheet date, but prior to the date of financial statement issuance. If an entity uses one or both of the practical expedient and/or accounting policy elections, disclosure is mandatory.
Conclusion
Lastly, such advice would be administered on a forward-looking basis, and both of these entities (PCC and FASB) will make the ultimate findings and guidelines of the implementation dates once industry professionals’ comments are considered. However, entities will likely be able to utilize these guidelines sooner.
For eligible companies, these standards could provide greater flexibility and the ability to divert resources to more productive allocations.
How Reporting Might be Less Complex in 2025
January 1, 2025 · Accounting News, Blog, Uncategorized
⏱ 4 min read
A Dec. 3 proposal from FASB’s Accounting Standards Update (ASU) might provide some flexibility for private businesses and select nonprofits. “Financial Instruments – Credit Losses (Topic 326)” looks at measuring credit losses for contract assets and accounts receivable for these entities.
When it comes to determining projected credit losses for current accounts receivables and current contract assets, businesses face immense resource needs and reporting requirements, including for assets acquired prior to the publication dates of financial statements.
With public comments being received through Jan. 17, 2025, industry professionals have reported that when it comes to gauging projected credit losses for current contract assets and current accounts receivable, there’s a massive undertaking and validation necessary for assets collected prior to financial statement issuance dates. Industry professionals argue that being able to factor in collections post-balance sheet date in calculating expected credit losses would reduce the complexity for preparers, whereas, for third parties, including investors and others who utilize financial statements, it would provide them with valuable data.
FASB proposed an amendment to ASC 326 207 to allow private companies and certain not-for-profit entities to employ a more flexible and efficient way to better gauge their projected credit losses for current contract assets and accounts receivable that originate from transaction accounts under ASC 606.
Working with the Private Company Council (PCC) to look at stakeholders’ concerns that estimating projected credit losses can be exorbitant and complicated for financial proceedings, FASB is soliciting comments on whether or not to expand the scope of entities included for ASU standards, along with different asset classes.
Current Criteria
According to ASC 326-20, when expected credit losses are estimated by entities, an entity must evaluate their ability to garner cash flows via the lens of contemporary economic circumstances, rational and documented projections, and past losses. Past losses may need to be fine-tuned to approximate project credit losses if past circumstances change from present conditions or from well-ground estimates and documented projections. Another consideration when formulating credit loss projections is that entities aren’t required to factor in collections obtained post-balance sheet date.
Proposed Additions
When it comes to the proposed additions, FASB speaks to a practical expedient and an accounting policy election. The practical expedient concerns an entity’s well-grounded, data-dependent projections. If an entity chooses the practical expedient, it would be able to factor in collection activity beyond the balance sheet date when projecting expected credit losses.
Practical Expedient
To formulate projections that are rational and based on verified accounting details, this so-called practical expedient can be chosen by the entity that assumes its present balance sheet conditions will last for the entire projection time frame. Choosing a practical expedient also implies that an entity’s accounting policy will factor in collection activity past its balance sheet date when gauging expected credit losses. Specifically, under 326-20-30-10C for the practical expedient, during the projection time frame, an entity will maintain the exact circumstances of the balance sheet throughout the rational and data-based projection period.
If a business, for example, has determined a particular client is facing monetary challenges, it would account for its client’s financial issues through projections of estimated expected credit losses for said client, even though it has not impacted the business’ historical loss experience or if the business is up to date as of the balance sheet date.
Accounting Policy Election
Per 326-20-30-10E, when a practical expedient from 326-20-30-10C through 30-10D is chosen by entities for their accounting policy election when projecting credit losses, it signals that the entity factors in collection activity after the balance sheet date, but prior to the date of financial statement issuance. If an entity uses one or both of the practical expedient and/or accounting policy elections, disclosure is mandatory.
Conclusion
Lastly, such advice would be administered on a forward-looking basis, and both of these entities (PCC and FASB) will make the ultimate findings and guidelines of the implementation dates once industry professionals’ comments are considered. However, entities will likely be able to utilize these guidelines sooner.
For eligible companies, these standards could provide greater flexibility and the ability to divert resources to more productive allocations.
Disclaimer
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
The Salt Typhoon cyberattack is among recent cyberattacks that reaffirm the urgent need for robust data security measures. This attack targeted major telecommunications providers, compromising critical infrastructure and potentially exposing vast amounts of sensitive data. With cyberthreats becoming more sophisticated, businesses and individuals must prioritize data security to maintain trust and compliance.
The Role of Apps in Managing and Protecting Client Data
Businesses need apps because they make the work easier and more organized. Apps help teams communicate better, manage tasks, and share information quickly, no matter where people are. The apps also simplify handling customer needs, improving service, and tracking business performance. Generally, apps save time while helping businesses work smarter and stay competitive.
One of the most critical uses of apps is managing client data. This data includes personal details like names and addresses. It also includes financial information such as bank details, as well as business-specific data like contracts and project plans. Losing or exposing this sensitive information can lead to severe consequences, including financial losses, legal penalties, and damaged reputations. Clients may lose trust in your business, leading to lost opportunities and reduced customer loyalty. By using apps effectively, businesses can better organize, safeguard, and utilize client data to build stronger relationships and maintain long-term success.
Encryption: A Critical Security Measure
Encryption has become crucial in modern data security. It transforms readable data into an unreadable format, ensuring only authorized parties can access the information. There are various types of encryptions, including end-to-end encryption (E2EE), which protects data during transmission, and at-rest encryption, which secures stored data.
Following the Salt Typhoon cyberattacks, the FBI and Cybersecurity and Infrastructure Security Agency (CISA) issued a joint advisory urging individuals and organizations to prioritize using encrypted communication channels. Given the vulnerability of traditional communication methods, the agencies strongly recommended adopting end-to-end encrypted messaging apps like Signal for secure communication. This recommendation aims to mitigate the risks associated with compromised telecommunication networks. It also helps protect sensitive information from unauthorized access. Even if cybercriminals intercept the data, they cannot decipher it without the encryption key. This layer of protection mitigates the risks of unauthorized access and data breaches, making encryption an essential tool for businesses.
The Role of Encrypted Apps
Enhanced security: Encrypted apps provide a critical layer of defense against sophisticated cyberattacks. By encrypting data both in transit and at rest, these apps ensure that even if communication networks are compromised, sensitive information remains inaccessible to attackers.
Compliance with regulations: With so many ongoing cyberattacks, regulatory scrutiny of data security practices has intensified. Encrypted apps can help businesses comply with relevant regulations, such as the GDPR and CCPA, by demonstrating a commitment to data protection.
Building trust and customer loyalty: Customers are increasingly wary of data breaches in an era of heightened cybersecurity concerns. Utilizing encrypted apps demonstrates a commitment to data security and privacy, fostering trust and loyalty among clients.
Protecting business operations: Encrypted apps are crucial for protecting client data and safeguarding critical business information, such as intellectual property, financial records, and internal communications. This ensures the continuity and integrity of business operations, even in the face of advanced cyber threats.
Choosing and Implementing Encrypted Apps
When selecting and implementing the right encrypted apps, it is important to consider them carefully. First, it is good to consider industry-specific needs as different industries have different data security needs. For example, while a healthcare provider must comply with Health Insurance Portability and Accountability Act (HIPAA) regulations, a business in the financial industry must adhere to banking regulations. This calls for selecting industry-specific apps.
Businesses also must prioritize apps with robust security features, such as strong encryption algorithms, multifactor authentication, and regular security updates. It is also important to carefully review the data privacy policies of app providers and ensure compliance with relevant regulations.
Effective employee training is also essential for successfully implementing encrypted apps. Employees must be educated on the importance of data security, the proper use of encrypted apps, and best practices for handling sensitive information.
Conclusion
Client data is one of a business’s most valuable assets, and protecting it is paramount. The growing threat of cyberattacks and the increasing complexity of data protection regulations make encryption an essential tool. By embracing encrypted communication channels, businesses can significantly enhance their resilience against sophisticated cyberattacks, protect sensitive client data, and maintain a competitive edge in today’s digital economy.
Securing Client Data: The Importance of Encrypted Apps
January 1, 2025 · Blog, Uncategorized, What’s New in Technology
⏱ 4 min read
The Salt Typhoon cyberattack is among recent cyberattacks that reaffirm the urgent need for robust data security measures. This attack targeted major telecommunications providers, compromising critical infrastructure and potentially exposing vast amounts of sensitive data. With cyberthreats becoming more sophisticated, businesses and individuals must prioritize data security to maintain trust and compliance.
The Role of Apps in Managing and Protecting Client Data
Businesses need apps because they make the work easier and more organized. Apps help teams communicate better, manage tasks, and share information quickly, no matter where people are. The apps also simplify handling customer needs, improving service, and tracking business performance. Generally, apps save time while helping businesses work smarter and stay competitive.
One of the most critical uses of apps is managing client data. This data includes personal details like names and addresses. It also includes financial information such as bank details, as well as business-specific data like contracts and project plans. Losing or exposing this sensitive information can lead to severe consequences, including financial losses, legal penalties, and damaged reputations. Clients may lose trust in your business, leading to lost opportunities and reduced customer loyalty. By using apps effectively, businesses can better organize, safeguard, and utilize client data to build stronger relationships and maintain long-term success.
Encryption: A Critical Security Measure
Encryption has become crucial in modern data security. It transforms readable data into an unreadable format, ensuring only authorized parties can access the information. There are various types of encryptions, including end-to-end encryption (E2EE), which protects data during transmission, and at-rest encryption, which secures stored data.
Following the Salt Typhoon cyberattacks, the FBI and Cybersecurity and Infrastructure Security Agency (CISA) issued a joint advisory urging individuals and organizations to prioritize using encrypted communication channels. Given the vulnerability of traditional communication methods, the agencies strongly recommended adopting end-to-end encrypted messaging apps like Signal for secure communication. This recommendation aims to mitigate the risks associated with compromised telecommunication networks. It also helps protect sensitive information from unauthorized access. Even if cybercriminals intercept the data, they cannot decipher it without the encryption key. This layer of protection mitigates the risks of unauthorized access and data breaches, making encryption an essential tool for businesses.
The Role of Encrypted Apps
Enhanced security: Encrypted apps provide a critical layer of defense against sophisticated cyberattacks. By encrypting data both in transit and at rest, these apps ensure that even if communication networks are compromised, sensitive information remains inaccessible to attackers.
Compliance with regulations: With so many ongoing cyberattacks, regulatory scrutiny of data security practices has intensified. Encrypted apps can help businesses comply with relevant regulations, such as the GDPR and CCPA, by demonstrating a commitment to data protection.
Building trust and customer loyalty: Customers are increasingly wary of data breaches in an era of heightened cybersecurity concerns. Utilizing encrypted apps demonstrates a commitment to data security and privacy, fostering trust and loyalty among clients.
Protecting business operations: Encrypted apps are crucial for protecting client data and safeguarding critical business information, such as intellectual property, financial records, and internal communications. This ensures the continuity and integrity of business operations, even in the face of advanced cyber threats.
Choosing and Implementing Encrypted Apps
When selecting and implementing the right encrypted apps, it is important to consider them carefully. First, it is good to consider industry-specific needs as different industries have different data security needs. For example, while a healthcare provider must comply with Health Insurance Portability and Accountability Act (HIPAA) regulations, a business in the financial industry must adhere to banking regulations. This calls for selecting industry-specific apps.
Businesses also must prioritize apps with robust security features, such as strong encryption algorithms, multifactor authentication, and regular security updates. It is also important to carefully review the data privacy policies of app providers and ensure compliance with relevant regulations.
Effective employee training is also essential for successfully implementing encrypted apps. Employees must be educated on the importance of data security, the proper use of encrypted apps, and best practices for handling sensitive information.
Conclusion
Client data is one of a business’s most valuable assets, and protecting it is paramount. The growing threat of cyberattacks and the increasing complexity of data protection regulations make encryption an essential tool. By embracing encrypted communication channels, businesses can significantly enhance their resilience against sophisticated cyberattacks, protect sensitive client data, and maintain a competitive edge in today’s digital economy.
Disclaimer
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
The Social Security Fairness Act of 2023, formally known as H.R. 82, aimed at ending two provisions in the Social Security system that affect public sector employees who have earned pensions from jobs not covered by Social Security. These provisions are the Windfall Elimination Provision and the Government Pension Offset, both of which reduce or eliminate Social Security benefits for workers who have worked in both public-sector and private-sector jobs.
The Problem: WEP and GPO
The Windfall Elimination Provision and the Government Pension Offset were originally designed to prevent public sector workers from receiving larger Social Security benefits than they would have been entitled to had they worked in jobs covered by Social Security for their entire careers. However, critics argue that these provisions disproportionately harm workers who have spent a significant portion of their careers in public service, such as teachers, police officers, firefighters, and other state and local government employees.
Windfall Elimination Provision (WEP):
The WEP reduces the Social Security benefits of individuals who have worked in both the private sector (where they paid into Social Security) and the public sector (where they often did not contribute to Social Security). Typically, Social Security benefits are based on an individual’s 35 highest-earning years. The WEP alters the formula used to calculate benefits for individuals with fewer than 30 years of substantial earnings in Social Security-covered employment, leading to a lower Social Security benefit than they would otherwise be entitled to. For many, this results in a significant reduction in the monthly payment they would have received under the standard Social Security formula.
Government Pension Offset (GPO):
The GPO affects spouses and widows/widowers of Social Security beneficiaries. Under this provision, individuals who receive a government pension from work that was not covered by Social Security (such as state or local government employees) see a reduction in their spousal or survivor benefits from Social Security. The offset is calculated by reducing the spousal or survivor benefit by an amount equal to two-thirds of the government pension. This can leave many public employees with little to no spousal or survivor benefits despite their spouse having paid into Social Security.
What H.R. 82 Seeks to Accomplish
By eliminating both the WEP and GPO, the bill aims to ensure that public sector workers who have earned Social Security benefits through their work in the private sector are not penalized by reductions in those benefits. It also seeks to provide fairer treatment for the spouses and survivors of government employees who may otherwise see their Social Security benefits reduced or eliminated entirely.
The bill has garnered bipartisan support, as lawmakers from both sides of the aisle recognize the fairness of eliminating these provisions, which many see as an unjust penalty against those who have dedicated their careers to public service. H.R. 82, if passed, would provide much-needed relief to millions of retirees, many of who are struggling with the financial impacts of these provisions.
Conclusion:
The introduction of H.R. 82, the Social Security Fairness Act of 2023, marks a crucial point in the ongoing debate over Social Security benefits for public sector workers. By eliminating the Windfall Elimination Provision and the Government Pension Offset, the bill would restore fairness and equity for millions of public employees who have spent their careers in service to their communities. As this bill progresses, it will likely remain a significant issue in discussions surrounding Social Security reform and the treatment of public sector employees.
President Joe Biden signed H.R. 82, the Social Security Fairness Act, into law on Sunday, January 5, 2025, at 3:00 p.m. Central Time Zone.
The Social Security Fairness Act of 2023: More Retirement Income for Teachers, Police, Firefighters & Gov. Workers
January 1, 2025 · Blog, Guest Article of the Month, Uncategorized
⏱ 3 min read
The Social Security Fairness Act of 2023, formally known as H.R. 82, aimed at ending two provisions in the Social Security system that affect public sector employees who have earned pensions from jobs not covered by Social Security. These provisions are the Windfall Elimination Provision and the Government Pension Offset, both of which reduce or eliminate Social Security benefits for workers who have worked in both public-sector and private-sector jobs.
The Problem: WEP and GPO
The Windfall Elimination Provision and the Government Pension Offset were originally designed to prevent public sector workers from receiving larger Social Security benefits than they would have been entitled to had they worked in jobs covered by Social Security for their entire careers. However, critics argue that these provisions disproportionately harm workers who have spent a significant portion of their careers in public service, such as teachers, police officers, firefighters, and other state and local government employees.
Windfall Elimination Provision (WEP):
The WEP reduces the Social Security benefits of individuals who have worked in both the private sector (where they paid into Social Security) and the public sector (where they often did not contribute to Social Security). Typically, Social Security benefits are based on an individual’s 35 highest-earning years. The WEP alters the formula used to calculate benefits for individuals with fewer than 30 years of substantial earnings in Social Security-covered employment, leading to a lower Social Security benefit than they would otherwise be entitled to. For many, this results in a significant reduction in the monthly payment they would have received under the standard Social Security formula.
Government Pension Offset (GPO):
The GPO affects spouses and widows/widowers of Social Security beneficiaries. Under this provision, individuals who receive a government pension from work that was not covered by Social Security (such as state or local government employees) see a reduction in their spousal or survivor benefits from Social Security. The offset is calculated by reducing the spousal or survivor benefit by an amount equal to two-thirds of the government pension. This can leave many public employees with little to no spousal or survivor benefits despite their spouse having paid into Social Security.
What H.R. 82 Seeks to Accomplish
By eliminating both the WEP and GPO, the bill aims to ensure that public sector workers who have earned Social Security benefits through their work in the private sector are not penalized by reductions in those benefits. It also seeks to provide fairer treatment for the spouses and survivors of government employees who may otherwise see their Social Security benefits reduced or eliminated entirely.
The bill has garnered bipartisan support, as lawmakers from both sides of the aisle recognize the fairness of eliminating these provisions, which many see as an unjust penalty against those who have dedicated their careers to public service. H.R. 82, if passed, would provide much-needed relief to millions of retirees, many of who are struggling with the financial impacts of these provisions.
Conclusion:
The introduction of H.R. 82, the Social Security Fairness Act of 2023, marks a crucial point in the ongoing debate over Social Security benefits for public sector workers. By eliminating the Windfall Elimination Provision and the Government Pension Offset, the bill would restore fairness and equity for millions of public employees who have spent their careers in service to their communities. As this bill progresses, it will likely remain a significant issue in discussions surrounding Social Security reform and the treatment of public sector employees.
President Joe Biden signed H.R. 82, the Social Security Fairness Act, into law on Sunday, January 5, 2025, at 3:00 p.m. Central Time Zone.
Disclaimer
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
No matter the type of business or industry, being able to analyze and deduce patterns is essential to discovering a business’ financial health. Here are four commonly used calculations to help internal and external stakeholders determine an organization’s ability to manage its finances.
Break-Even Analysis
This formula analyzes fixed costs versus the profitability a business earns for every extra item it creates and sells.
Businesses that have smaller thresholds to meet their fixed costs to realize profitability have an easier break-even point to meet and exceed. Once the fixed costs threshold is satisfied and sales revenue outpaces variable costs, a business will know when it hits the break-even point.
Break Even Point (BEP) = Total Fixed Costs/(Price Per Unit – Variable Cost Per Unit)
This takes the total fixed costs divided by the price per individual unit minus each unit’s variable cost.
Examples of fixed costs are rent, taxes, insurance and wages. Examples of variable costs are raw materials, production supplies, utilities and packaging.
Another way to determine a company’s break-even point is as follows:
Contribution Margin = Item Price – Variable Cost Per Unit
This is illustrated by: $55 = ($85 – $30)
The item’s priced at $85, with a variable cost of $30, the contribution margin is $55 of how much revenue a company earns to pay for the remaining fixed costs.
Cash Ratio Formula
The cash ratio formula offers one way to look at a company’s liquidity position by comparing a company’s cash and cash equivalents to its current liabilities or debts due within the next 12 months. It shows how well positioned a business is (or is not) able to pay debts due within 12 months, and to satisfy the near-term obligations of its long-term debt.
It’s an important ratio that lenders look at when evaluating a company’s loan application. Instead of including assets such as accounts receivables, it factors in a business’ ability to take care of its financial obligations. It’s thought of as being a more real world look at how financially stable a business is.
This is defined as all income minus the cost of goods sold (COGS). COGS is comprised of expenses attributable to the creation of products, which include input materials and salaries for workers to produce such goods. However, it excludes expenses for taxes, overhead, debt, asset acquisitions, etc., among others. Another way to explain this calculation is to ask how much a business retains as profit once production costs are accounted for.
It’s calculated as follows: Gross Profit Margin = [(Net Sales – Cost of Goods Sold)/(New Sales)] x 100
Debt-to-Equity (D/E) Ratio
This is used to determine how much debt or financial leverage a company has on its books. It tells internal stakeholders and external parties what percentage of debt a company is using to operate compared to the business’ available operating reserves. This ratio contrasts a business’ complete financial obligations against its shareholder equity. Its primary use is to see how extensively it uses debt to operate.
It’s calculated as follows: Debt/Equity Ratio = Total Liabilities/Total Shareholders’ Equity.
While these calculations may seem straightforward, these are only a few examples of how businesses can calculate and analyze a company’s position – be it the owner, an employee or an outside lender or investor.
Common Business Accounting Calculations
December 1, 2024 · Blog, General Business News, Uncategorized
⏱ 3 min read
No matter the type of business or industry, being able to analyze and deduce patterns is essential to discovering a business’ financial health. Here are four commonly used calculations to help internal and external stakeholders determine an organization’s ability to manage its finances.
Break-Even Analysis
This formula analyzes fixed costs versus the profitability a business earns for every extra item it creates and sells.
Businesses that have smaller thresholds to meet their fixed costs to realize profitability have an easier break-even point to meet and exceed. Once the fixed costs threshold is satisfied and sales revenue outpaces variable costs, a business will know when it hits the break-even point.
Break Even Point (BEP) = Total Fixed Costs/(Price Per Unit – Variable Cost Per Unit)
This takes the total fixed costs divided by the price per individual unit minus each unit’s variable cost.
Examples of fixed costs are rent, taxes, insurance and wages. Examples of variable costs are raw materials, production supplies, utilities and packaging.
Another way to determine a company’s break-even point is as follows:
Contribution Margin = Item Price – Variable Cost Per Unit
This is illustrated by: $55 = ($85 – $30)
The item’s priced at $85, with a variable cost of $30, the contribution margin is $55 of how much revenue a company earns to pay for the remaining fixed costs.
Cash Ratio Formula
The cash ratio formula offers one way to look at a company’s liquidity position by comparing a company’s cash and cash equivalents to its current liabilities or debts due within the next 12 months. It shows how well positioned a business is (or is not) able to pay debts due within 12 months, and to satisfy the near-term obligations of its long-term debt.
It’s an important ratio that lenders look at when evaluating a company’s loan application. Instead of including assets such as accounts receivables, it factors in a business’ ability to take care of its financial obligations. It’s thought of as being a more real world look at how financially stable a business is.
This is defined as all income minus the cost of goods sold (COGS). COGS is comprised of expenses attributable to the creation of products, which include input materials and salaries for workers to produce such goods. However, it excludes expenses for taxes, overhead, debt, asset acquisitions, etc., among others. Another way to explain this calculation is to ask how much a business retains as profit once production costs are accounted for.
It’s calculated as follows: Gross Profit Margin = [(Net Sales – Cost of Goods Sold)/(New Sales)] x 100
Debt-to-Equity (D/E) Ratio
This is used to determine how much debt or financial leverage a company has on its books. It tells internal stakeholders and external parties what percentage of debt a company is using to operate compared to the business’ available operating reserves. This ratio contrasts a business’ complete financial obligations against its shareholder equity. Its primary use is to see how extensively it uses debt to operate.
It’s calculated as follows: Debt/Equity Ratio = Total Liabilities/Total Shareholders’ Equity.
While these calculations may seem straightforward, these are only a few examples of how businesses can calculate and analyze a company’s position – be it the owner, an employee or an outside lender or investor.
Disclaimer
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
All bills not enacted by the end of the 118th congressional session on Jan. 3, 2025, will expire.
Social Security Fairness Act of 2023 (HR 82) – This bill, with 330 bipartisan sponsors and a similar bill in the Senate, was introduced by Rep. Garret Graves (R-LA) on Jan. 9, 2023. It passed in the House on Nov. 12 of this year and is likely to pass in the Senate before the year’s end. The purpose of the bill is to eliminate the government pension offset that reduces Social Security benefits for individuals who receive other benefits, such as a pension from a state or local government. In the private sector, this would have a similar effect to withholding Social Security from people who have a 401(k). The bill would also repeal provisions that reduce Social Security benefits for spouses and widows/ers who receive their own government pensions. The provisions of the bill would be retroactive to the beginning of 2024.
BOLIVAR Act (HR 825) – This legislation prohibits the head of an executive agency to enter into a contract for the procurement of goods or services with any person that has business operations with the Maduro regime in Venezuela. The act was introduced on Feb. 2, 2023, by Rep. Michael Waltz (R-OH). It passed in the House on Nov. 18, and its fate currently lies with the Senate.
Vote by Mail Tracking Act (HR 5658) – This bill would require mail-in ballots to use the Postal Service barcode and an Official Election Mail logo. It passed in the House on Nov. 18 and is under consideration in the Senate. The bill was introduced by Rep. Katie Porter (D-CA) on Sept. 21, 2023.
Find and Protect Foster Youth Act (S 1146) – This act was introduced on March 30, 2023, by Sen. John Cornyn (R-TX). It would amend a provision of the Social Security Act to require the Department of Health and Human Services to eliminate obstacles to identifying and responding to reports of missing foster care children. Furthermore, it would assist in the assessment and screening of children who are at risk of becoming victims of sex trafficking, as well as identify best practices for effective interventions. The bipartisan bill passed in the House on Nov. 18 and is currently in the Senate.
Billion Dollar Boondoggle Act of 2023 (S 1228) – This bill was introduced by Sen. Joni Ernst (R-IA) on April 25, 2023. The bill would require the director of the Office of Management and Budget to submit an annual report to Congress detailing projects that are over budget and behind schedule. This is a bipartisan bill that has passed in both the Senate and the House, but on July 22, the House made changes and sent it back to the Senate, where it currently resides.
Rural Broadband Protection Act of 2024 (S 275) – Introduced by Sen. Shelley Moore Capito (R-WV) on Feb. 7, 2023, this bill would require the Federal Communications Commission (FCC) to vet applicants for funding of affordable broadband deployment in high-cost areas (including rural communities). The FCC would mandate a process, including a detailed proposal with technical capabilities to provide competitive awards for implementing the broadband network services. The FCC would then assess proposals in line with well-established technical standards. The bill passed the Senate on Sept. 25 and is currently with the House.
Making Pensions Equitable, Protecting Foster Kids, Mail-in Votes and Tracking Government Spending
December 1, 2024 · Blog, Congress at Work, Uncategorized
⏱ 3 min read
All bills not enacted by the end of the 118th congressional session on Jan. 3, 2025, will expire.
Social Security Fairness Act of 2023 (HR 82) – This bill, with 330 bipartisan sponsors and a similar bill in the Senate, was introduced by Rep. Garret Graves (R-LA) on Jan. 9, 2023. It passed in the House on Nov. 12 of this year and is likely to pass in the Senate before the year’s end. The purpose of the bill is to eliminate the government pension offset that reduces Social Security benefits for individuals who receive other benefits, such as a pension from a state or local government. In the private sector, this would have a similar effect to withholding Social Security from people who have a 401(k). The bill would also repeal provisions that reduce Social Security benefits for spouses and widows/ers who receive their own government pensions. The provisions of the bill would be retroactive to the beginning of 2024.
BOLIVAR Act (HR 825) – This legislation prohibits the head of an executive agency to enter into a contract for the procurement of goods or services with any person that has business operations with the Maduro regime in Venezuela. The act was introduced on Feb. 2, 2023, by Rep. Michael Waltz (R-OH). It passed in the House on Nov. 18, and its fate currently lies with the Senate.
Vote by Mail Tracking Act (HR 5658) – This bill would require mail-in ballots to use the Postal Service barcode and an Official Election Mail logo. It passed in the House on Nov. 18 and is under consideration in the Senate. The bill was introduced by Rep. Katie Porter (D-CA) on Sept. 21, 2023.
Find and Protect Foster Youth Act (S 1146) – This act was introduced on March 30, 2023, by Sen. John Cornyn (R-TX). It would amend a provision of the Social Security Act to require the Department of Health and Human Services to eliminate obstacles to identifying and responding to reports of missing foster care children. Furthermore, it would assist in the assessment and screening of children who are at risk of becoming victims of sex trafficking, as well as identify best practices for effective interventions. The bipartisan bill passed in the House on Nov. 18 and is currently in the Senate.
Billion Dollar Boondoggle Act of 2023 (S 1228) – This bill was introduced by Sen. Joni Ernst (R-IA) on April 25, 2023. The bill would require the director of the Office of Management and Budget to submit an annual report to Congress detailing projects that are over budget and behind schedule. This is a bipartisan bill that has passed in both the Senate and the House, but on July 22, the House made changes and sent it back to the Senate, where it currently resides.
Rural Broadband Protection Act of 2024 (S 275) – Introduced by Sen. Shelley Moore Capito (R-WV) on Feb. 7, 2023, this bill would require the Federal Communications Commission (FCC) to vet applicants for funding of affordable broadband deployment in high-cost areas (including rural communities). The FCC would mandate a process, including a detailed proposal with technical capabilities to provide competitive awards for implementing the broadband network services. The FCC would then assess proposals in line with well-established technical standards. The bill passed the Senate on Sept. 25 and is currently with the House.
Disclaimer
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
What do you consider to be your purpose in this world? Few people think about their life that way. In Japan, they call it your ikigai. In France, they refer to your raison d’etre. For Americans, that roughly translates to your purpose in life or your reason for being.
It’s easy to consider your family or even your career as your reason to live. But true embracement of the ikigai concept is more of a lifestyle, not a specific person, place or thing.
Your purpose may not even be something you’ve pursued in your adult life. Many of us follow the socially expected path: higher education, a good job, a rewarding career, marriage, home, and family. But those things are not everyone’s raison d’etre. They might wake up one morning thinking that once they’ve achieved all those goals, they will finally get the chance to do the one they’ve always wanted. What is that?
The older we get, the more we lose a spouse or life partner, siblings, or children – and those who retire no longer have work to feel fulfilled. As part of your retirement planning effort, consider life without any of those things. How would you bear it? If you outlive your career and loved ones, what would you do?
Note that your ikigai does not insulate you from bad things happening. Instead, it’s the thing you look forward to when the smoke clears: the light at the end of the tunnel. On balance, it’s the thing that helps get you through the pain and restores happiness. In fact, discovering your raison d’etre can help you better cope with stress and loss. People who pursue their ikigai tend to have better mental health, experience fewer chronic diseases, and are more likely to live longer.
Oftentimes ikigai is felt as part of a process. For example, the joy of mixing ingredients to prepare baked goods or a meal. Planting a garden. Rebuilding an engine. It can be the process of writing or painting or playing an instrument, but not necessarily finishing a novel or singing in public. It can be as simple as finding joy in daily activities, nurturing relationships or doing community service.
Another advantage to ikigai is that it can connect you with other people who share your passion, which can be very important as you grow older and more isolated. By leaning into your ikigai, you could expand your social network with connections that are meaningful and fulfilling.
For some people, their raison d’etre is spiritual. A belief and perhaps a greater connection to a higher being. They may wish to spend more time becoming involved in church activities, reading scripture that supports their religion, or even exploring other religions.
The Japanese culture believes that each individual has an inherent ikigai based on their personal values and beliefs. One way to think about it is as your philosophy on life. Since this step is a part of retirement planning, it is fortunate that you have lived long enough to have developed some philosophies on life.
For example, some people discover that family does not just consist of blood relatives. Instead, their concept of family is people who are there through good and bad times, who always show love and respect, who you can rely on. Those things might not always be true among family members who meet the traditional definition. This type of ikigai may help you recognize that the death of loved ones does not necessarily mean you lose your family. You can always build and add to your family (e.g., neighbors and friends, fostering children or pets, big brother/big sister programs).
How Do You Find Your Ikigai??
Many times, the hustle and bustle of life keeps us from finding our true purpose. We proceed as loyal soldiers down a path prescribed by society instead of pursuing things that may bring us greater happiness. There’s nothing wrong with a career and family, but there is likely something more that each of us can pursue that is personal and soul-enriching. Sometimes, you can discover your raison d’etre by exploring your passions, values, strengths, and skills. For example, ask yourself the following questions:
When I was a child, I loved doing…
If money didn’t matter, I would be…
If I believed I could not fail, I would…
I completely lose track of time when I am…
I am most happy with who I am when I…
I am really good at…
If I didn’t care what others thought, I would…
In my free time, I love to…
If I had only six months to live, I would spend my time…
If I were to die tomorrow, I would regret that I did not…
Consider hobbies or classes that you’ve always wanted to try or past experiences or achievements that gave you a sense of satisfaction and fulfillment. Recall where you have found inspiration in the past, and pinpoint what lies at the cross-section of doing what you love and doing what you’re good at.
Remember that your reason for living is more of a journey, not a destination. Finding your ikigai may take a lifetime to discover, so don’t be afraid to try out different pursuits. In fact, your reason for being may simply be to try new things.
Pre-Retirement Planning Guide – Finding Purpose In Life
December 1, 2024 · Blog, Financial Planning, Uncategorized
⏱ 5 min read
Step 7: Find Your Raison d’Etre
What do you consider to be your purpose in this world? Few people think about their life that way. In Japan, they call it your ikigai. In France, they refer to your raison d’etre. For Americans, that roughly translates to your purpose in life or your reason for being.
It’s easy to consider your family or even your career as your reason to live. But true embracement of the ikigai concept is more of a lifestyle, not a specific person, place or thing.
Your purpose may not even be something you’ve pursued in your adult life. Many of us follow the socially expected path: higher education, a good job, a rewarding career, marriage, home, and family. But those things are not everyone’s raison d’etre. They might wake up one morning thinking that once they’ve achieved all those goals, they will finally get the chance to do the one they’ve always wanted. What is that?
The older we get, the more we lose a spouse or life partner, siblings, or children – and those who retire no longer have work to feel fulfilled. As part of your retirement planning effort, consider life without any of those things. How would you bear it? If you outlive your career and loved ones, what would you do?
Note that your ikigai does not insulate you from bad things happening. Instead, it’s the thing you look forward to when the smoke clears: the light at the end of the tunnel. On balance, it’s the thing that helps get you through the pain and restores happiness. In fact, discovering your raison d’etre can help you better cope with stress and loss. People who pursue their ikigai tend to have better mental health, experience fewer chronic diseases, and are more likely to live longer.
Oftentimes ikigai is felt as part of a process. For example, the joy of mixing ingredients to prepare baked goods or a meal. Planting a garden. Rebuilding an engine. It can be the process of writing or painting or playing an instrument, but not necessarily finishing a novel or singing in public. It can be as simple as finding joy in daily activities, nurturing relationships or doing community service.
Another advantage to ikigai is that it can connect you with other people who share your passion, which can be very important as you grow older and more isolated. By leaning into your ikigai, you could expand your social network with connections that are meaningful and fulfilling.
For some people, their raison d’etre is spiritual. A belief and perhaps a greater connection to a higher being. They may wish to spend more time becoming involved in church activities, reading scripture that supports their religion, or even exploring other religions.
The Japanese culture believes that each individual has an inherent ikigai based on their personal values and beliefs. One way to think about it is as your philosophy on life. Since this step is a part of retirement planning, it is fortunate that you have lived long enough to have developed some philosophies on life.
For example, some people discover that family does not just consist of blood relatives. Instead, their concept of family is people who are there through good and bad times, who always show love and respect, who you can rely on. Those things might not always be true among family members who meet the traditional definition. This type of ikigai may help you recognize that the death of loved ones does not necessarily mean you lose your family. You can always build and add to your family (e.g., neighbors and friends, fostering children or pets, big brother/big sister programs).
How Do You Find Your Ikigai??
Many times, the hustle and bustle of life keeps us from finding our true purpose. We proceed as loyal soldiers down a path prescribed by society instead of pursuing things that may bring us greater happiness. There’s nothing wrong with a career and family, but there is likely something more that each of us can pursue that is personal and soul-enriching. Sometimes, you can discover your raison d’etre by exploring your passions, values, strengths, and skills. For example, ask yourself the following questions:
When I was a child, I loved doing…
If money didn’t matter, I would be…
If I believed I could not fail, I would…
I completely lose track of time when I am…
I am most happy with who I am when I…
I am really good at…
If I didn’t care what others thought, I would…
In my free time, I love to…
If I had only six months to live, I would spend my time…
If I were to die tomorrow, I would regret that I did not…
Consider hobbies or classes that you’ve always wanted to try or past experiences or achievements that gave you a sense of satisfaction and fulfillment. Recall where you have found inspiration in the past, and pinpoint what lies at the cross-section of doing what you love and doing what you’re good at.
Remember that your reason for living is more of a journey, not a destination. Finding your ikigai may take a lifetime to discover, so don’t be afraid to try out different pursuits. In fact, your reason for being may simply be to try new things.
Disclaimer
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
Yep, it’s the end of another year! Chances are, you didn’t keep every resolution you made last year, for example, those goals about working out. (No shame here; we all do this!) However, the good news is that your fiscal goals can be a bit easier to achieve. Here are a few financial resolutions that are no-brainers, simple, and, best of all, no sweat.
Get a snapshot of your net worth. This is critical. Sit down and calculate this. When you know how much you have in terms of assets and liabilities, you can more easily determine where you need to make changes to your budget. For instance, this might be spending less on dining out and stocking more away in savings and investments. Understanding how much you have to work with is the first step to reaching your goals.
Pay off credit cards. This might well be an ongoing task, but the end of the year is a great time to take a breath, make a plan, and hit the ground running in the new year. If you have high-interest cards, look for limited-time, lower-interest and/or zero-interest cards. Some lenders will even give you as long as 21 months without interest. If you find yourself using credit cards more than you like, another way to get a handle on this is to use cash when you’re out at stores and restaurants. Seeing the dollars actually leaving your hands as opposed to just swiping your plastic might give you a needed dose of reality.
Update your savings goals. If you want to easily increase your savings, choose an amount and have it auto-drafted from your paycheck or checking account into your savings every month. This way, you’ll learn to live on the amount you have left. When you never see the amount you’re tucking away, you won’t miss it.
Review and reset your investments. Take some time to pull together all your assets: IRAs, retirement accounts, and employer 401(k) plans. If you can contribute more to any of these, all the better. For 401(k)s, the IRS just announced a cost-of-living adjustment for retirement plans and IRAs – the 401(k) contribution limit for 2025 is $23,500, up from $23,000 in 2024. However, individual retirement account (IRA) contributions will continue to be $7,000 in 2025, the same as in 2024. If you’re over 50, here’s some good news: You’ll be able to make even larger catch-up contributions than other workers because of a provision in Secure 2.0, a federal retirement law. Beginning in 2025, employees aged 60, 61, 62, or 63 who participate in workplace retirement plans can make catch-up contributions of up to $11,250.
Take a look at your credit report. This is key. You’re entitled to one free credit report a year from each of the three credit agencies, so doing this is easy peasy. Pull up your report and give it a look-see. If you see anything negative, take action to repair it. If there are any errors, correct them asap. To get started, go to AnnualCreditReport.com.
While there are many other money-related resolutions you can make, starting with ones that take minimal effort while yielding maximum results is a good place to begin, not to mention, a great way ease into the new year.
5 New Year’s Financial Resolutions You Can Actually Keep
December 1, 2024 · Blog, Tip of the Month, Uncategorized
⏱ 3 min read
Yep, it’s the end of another year! Chances are, you didn’t keep every resolution you made last year, for example, those goals about working out. (No shame here; we all do this!) However, the good news is that your fiscal goals can be a bit easier to achieve. Here are a few financial resolutions that are no-brainers, simple, and, best of all, no sweat.
Get a snapshot of your net worth. This is critical. Sit down and calculate this. When you know how much you have in terms of assets and liabilities, you can more easily determine where you need to make changes to your budget. For instance, this might be spending less on dining out and stocking more away in savings and investments. Understanding how much you have to work with is the first step to reaching your goals.
Pay off credit cards. This might well be an ongoing task, but the end of the year is a great time to take a breath, make a plan, and hit the ground running in the new year. If you have high-interest cards, look for limited-time, lower-interest and/or zero-interest cards. Some lenders will even give you as long as 21 months without interest. If you find yourself using credit cards more than you like, another way to get a handle on this is to use cash when you’re out at stores and restaurants. Seeing the dollars actually leaving your hands as opposed to just swiping your plastic might give you a needed dose of reality.
Update your savings goals. If you want to easily increase your savings, choose an amount and have it auto-drafted from your paycheck or checking account into your savings every month. This way, you’ll learn to live on the amount you have left. When you never see the amount you’re tucking away, you won’t miss it.
Review and reset your investments. Take some time to pull together all your assets: IRAs, retirement accounts, and employer 401(k) plans. If you can contribute more to any of these, all the better. For 401(k)s, the IRS just announced a cost-of-living adjustment for retirement plans and IRAs – the 401(k) contribution limit for 2025 is $23,500, up from $23,000 in 2024. However, individual retirement account (IRA) contributions will continue to be $7,000 in 2025, the same as in 2024. If you’re over 50, here’s some good news: You’ll be able to make even larger catch-up contributions than other workers because of a provision in Secure 2.0, a federal retirement law. Beginning in 2025, employees aged 60, 61, 62, or 63 who participate in workplace retirement plans can make catch-up contributions of up to $11,250.
Take a look at your credit report. This is key. You’re entitled to one free credit report a year from each of the three credit agencies, so doing this is easy peasy. Pull up your report and give it a look-see. If you see anything negative, take action to repair it. If there are any errors, correct them asap. To get started, go to AnnualCreditReport.com.
While there are many other money-related resolutions you can make, starting with ones that take minimal effort while yielding maximum results is a good place to begin, not to mention, a great way ease into the new year.
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
Also known as greenhouse gas (GHG) accounting, carbon accounting is a way for managers and analysts to measure a company’s total carbon emissions.
It’s a comprehensive approach to analyze how a company uses energy for its buildings, offices, conveyances and production processes. Carbon accounting examines firsthand, secondhand and tertiary energy uses.
Environmental, Social & Governance
Looking at ESG standards (Environmental, Social & Governance), it’s not only becoming encouraged, it’s becoming required for businesses, especially for publicly traded businesses. Whether it’s the U.S. Securities and Exchange Commission (SEC) or other governmental agencies in the global economy, these administrative organizations are mandating emission declarations for businesses to account for their carbon emissions. It’s also necessary for third parties (lenders, potential and current investors) to review and analyze a company’s current and past performance, along with industry comparisons.
It’s important to distinguish the differences between carbon and GHG accounting. Carbon accounting only looks at carbon dioxide emissions, while GHG looks at the broader category and illustrates why doing so is important. Businesses look at nitrous oxide and hydrofluorocarbons (HFCs), for example, when accounting for GHGs. However, such measurement is based on the so-called carbon dioxide equivalent or C02e. This helps standardize GHGs into the C02e standard for carbon accounting, giving government and interested parties the ability to measure across a universal standard. Two common uses for this standard are for carbon offsets and credits.
Calculating Emissions
1. Scope 1 factors in emissions from the company’s directly controlled or owned assets. Examples include factories, production, conveyances, etc.
2. Scope 2 looks at what the business uses in regard to climate-controlled services for their factories, offices, etc. It also looks at the company’s contracts with power suppliers.
3. Scope 3 factors in indirect emissions the business may incur. This includes commercial commuting activities, investing, how assets are disposed of, etc.
According to the SEC, Scope 3 emissions must include those “upstream and downstream activities in a company’s value chain” if they’re necessary for investor consideration or if the business has pledged to meet certain metrics for Scope 3 levels.
From there, a business’ activity metrics are calculated according to governmental and industry standards, such as the U.S. Environmental Protection Agency, ISO Standard 14064, or The Climate Registry’s General Reporting Protocol, etc. Businesses’ results are presented against past results, where they discuss how they will improve their efficiency internally and work with their supply chain partners.
Compliance
While compliance is one important reason, third-party audiences, such as family offices, institutional money managers, lenders, etc., are equally as important. Asset managers and family offices, for example, look for ESG or environmentally friendly investments to attract retail or “smart-money” investors. Similarly, activist investors, especially those looking to make companies more environmentally friendly, can look at companies to see how their carbon emissions stack up against their industry and overall commercial peers.
Another consideration is that by meeting regulatory or industry requirements and meeting ESG standards, businesses could qualify for preferential or market rates for funding from the debt markets.
Conclusion
The more companies are well-versed in this type of accounting, the better they will meet government and investor expectations.
Understanding Carbon Accounting
December 1, 2024 · Accounting News, Blog, Uncategorized
⏱ 3 min read
Also known as greenhouse gas (GHG) accounting, carbon accounting is a way for managers and analysts to measure a company’s total carbon emissions.
It’s a comprehensive approach to analyze how a company uses energy for its buildings, offices, conveyances and production processes. Carbon accounting examines firsthand, secondhand and tertiary energy uses.
Environmental, Social & Governance
Looking at ESG standards (Environmental, Social & Governance), it’s not only becoming encouraged, it’s becoming required for businesses, especially for publicly traded businesses. Whether it’s the U.S. Securities and Exchange Commission (SEC) or other governmental agencies in the global economy, these administrative organizations are mandating emission declarations for businesses to account for their carbon emissions. It’s also necessary for third parties (lenders, potential and current investors) to review and analyze a company’s current and past performance, along with industry comparisons.
It’s important to distinguish the differences between carbon and GHG accounting. Carbon accounting only looks at carbon dioxide emissions, while GHG looks at the broader category and illustrates why doing so is important. Businesses look at nitrous oxide and hydrofluorocarbons (HFCs), for example, when accounting for GHGs. However, such measurement is based on the so-called carbon dioxide equivalent or C02e. This helps standardize GHGs into the C02e standard for carbon accounting, giving government and interested parties the ability to measure across a universal standard. Two common uses for this standard are for carbon offsets and credits.
Calculating Emissions
1. Scope 1 factors in emissions from the company’s directly controlled or owned assets. Examples include factories, production, conveyances, etc.
2. Scope 2 looks at what the business uses in regard to climate-controlled services for their factories, offices, etc. It also looks at the company’s contracts with power suppliers.
3. Scope 3 factors in indirect emissions the business may incur. This includes commercial commuting activities, investing, how assets are disposed of, etc.
According to the SEC, Scope 3 emissions must include those “upstream and downstream activities in a company’s value chain” if they’re necessary for investor consideration or if the business has pledged to meet certain metrics for Scope 3 levels.
From there, a business’ activity metrics are calculated according to governmental and industry standards, such as the U.S. Environmental Protection Agency, ISO Standard 14064, or The Climate Registry’s General Reporting Protocol, etc. Businesses’ results are presented against past results, where they discuss how they will improve their efficiency internally and work with their supply chain partners.
Compliance
While compliance is one important reason, third-party audiences, such as family offices, institutional money managers, lenders, etc., are equally as important. Asset managers and family offices, for example, look for ESG or environmentally friendly investments to attract retail or “smart-money” investors. Similarly, activist investors, especially those looking to make companies more environmentally friendly, can look at companies to see how their carbon emissions stack up against their industry and overall commercial peers.
Another consideration is that by meeting regulatory or industry requirements and meeting ESG standards, businesses could qualify for preferential or market rates for funding from the debt markets.
Conclusion
The more companies are well-versed in this type of accounting, the better they will meet government and investor expectations.
Disclaimer
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
 Whether you file your income tax return early or at the last minute, there are ways to simplify the process and reduce what you owe – or even increase your refund – before the deadline.



 Here we are in yet another new year. The obligations and celebrations are over. Chances are, you’ve spent a fair amount over the holidays and might need a plan to help kickstart 2025 with some actionable financial goals. Here are a few ideas.
 A Dec. 3 proposal from FASB’s Accounting Standards Update (ASU) might provide some flexibility for private businesses and select nonprofits. “Financial Instruments – Credit Losses (Topic 326)” looks at measuring credit losses for contract assets and accounts receivable for these entities.
 The
 The Social Security Fairness Act of 2023, formally known as H.R. 82, aimed at ending two provisions in the Social Security system that affect public sector employees who have earned pensions from jobs not covered by Social Security. These provisions are the Windfall Elimination Provision and the Government Pension Offset, both of which reduce or eliminate Social Security benefits for workers who have worked in both public-sector and private-sector jobs.
 No matter the type of business or industry, being able to analyze and deduce patterns is essential to discovering a business’ financial health. Here are four commonly used calculations to help internal and external stakeholders determine an organization’s ability to manage its finances.
 All bills not enacted by the end of the 118th congressional session on Jan. 3, 2025, will expire.
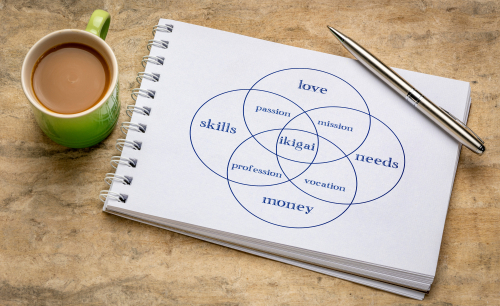 Step 7: Find Your Raison d’Etre
 Yep, it’s the end of another year! Chances are, you didn’t keep every resolution you made last year, for example, those goals about working out. (No shame here; we all do this!) However, the good news is that your fiscal goals can be a bit easier to achieve. Here are a few financial resolutions that are no-brainers, simple, and, best of all, no sweat.
 Also known as greenhouse gas (GHG) accounting, carbon accounting is a way for managers and analysts to measure a company’s total carbon emissions.